

Top Tech Companies in Pune (1,442)
We are a mobility company that innovates like a start-up and thinks like a technology company. This helps us anticipate change in one of the most complex industries in the world and respond quickly. We depend on a team of 171,000 dynamic, entrepreneurial-minded employees in an environment where great ideas flourish. Our presence spans 343 manufacturing operations and 88 product...

Magna International's Top Stability & Growth Strengths
Profitability: Adjusted earnings are rising faster than sales, with Q2 2026 adjusted EBIT at $677M versus $583M and adjusted EPS at $1.86 versus $1.44, and the 2026 outlook targets a higher adjusted EBIT margin. These results indicate improved earnings quality alongside only modest top-line expansion.
Healthy Cash Flow: Cash generation is robust, with first-half 2026 free cash flow near $1.0B and full-year guidance of $1.75–$1.85B, following strong cash flow in 2025. This points to strengthening liquidity and funding capacity even without rapid revenue growth.
Cost & Operational Efficiency: Earnings improvements are attributed to productivity initiatives and other operating factors, and margins expanded while sales increased only slightly. This suggests better conversion of revenue into operating profit.
Zocdoc is the tech company at the beginning of a better healthcare experience. Each month, millions of patients use Zocdoc to find in-network neighborhood doctors, instantly book appointments online, see what other real patients have to say, get reminders for upcoming appointments and preventive check-ups, fill out their paperwork online, and more.
Zocdoc's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have grown at a robust compound rate over multiple years, with momentum described as accelerating as of 2026. Company updates and industry reporting consistently point to ongoing top-line expansion alongside network scale-up.
Profitability: The company indicates it has been annually profitable since 2023 and cash-flow positive, and it cites performance above the 'Rule of 40' benchmark in 2025. This signals growth paired with financial discipline rather than expansion funded by sustained losses.
Strategic Partnerships: The Care Access Network extends booking into platforms including Amazon Health AI, Google Gemini, Yelp, Healthgrades, and Blue Shield of California. Partner implementations are described as materially increasing booked appointments and expanding available bookable hours, indicating traction beyond the core site.

By automating and streamlining common accounting workflows to make them more efficient, FloQast is where accounting teams want to work so they can focus on what matters most, even when that’s just logging off on time. Whether automating reconciliations, documentation requests, or streamlining recurring accounting processes, such as the month-end close, financial reporting, or payroll, FloQast's platform enhances the way...
FloQast's Top Stability & Growth Strengths
Strong Revenue Growth: ARR increased from $100M in early 2024 to over $200M by January 2026, and placement on Deloitte’s Technology Fast 500 signals substantial multi‑year expansion. While full audited statements aren’t public, these recurring‑revenue milestones and independent rankings indicate material scale-up.
Innovation-Driven Growth: AI-powered accounting Agents introduced in 2025 are cited as driving enterprise adoption and expanding automation across recurring workflows. Product development beyond close management supports broader accounting operations use cases.
Market Expansion: International reach broadened with offices in London and Sydney and reported momentum across EMEA. A managed-services agreement with EY and a push into larger enterprises point to widening market access.
We're honored to be No. 10 on Great Place to Work's World's Best Workplaces and recognized in the Fortune 100 Best Companies to Work For® list in 2025. At MetLife, we're leading the global transformation of an industry we’ve defined for over 157 years. At MetLife, every innovation and line of code is a lifeline for our customers and their...

MetLife's Top Stability & Growth Strengths
Strong Revenue Growth: Financial results show year-over-year increases in premiums, fees and other revenues in 2025 and in the first two quarters of 2026. Regulatory filings also indicate total revenue rose versus the prior year, reinforcing ongoing top-line momentum.
Profitability: Adjusted earnings and earnings per share accelerated faster than revenue across multiple periods, with adjusted return on equity within management’s stated target range. This points to improving underlying profitability even as reported results can be affected by market-sensitive items.
Market Expansion: Growth was reported across Group Benefits, Asia, Latin America, EMEA and the investment management business, indicating broad-based expansion. Sales and adjusted revenue excluding pension risk transfers also increased, suggesting momentum beyond one-off transactions.
Mastercard powers economies and empowers people in 200+ countries and territories worldwide. Together with our customers, we’re building a resilient economy where everyone can prosper. We support a wide range of digital payments choices, making transactions secure, simple, smart and accessible. Our technology and innovation, partnerships and networks combine to deliver a unique set of products and services that help...

Mastercard's Top Stability & Growth Strengths
Strong Revenue Growth: Net revenue rose 16% in 2025 and increased 14% year over year in Q2 2026, alongside gains in gross dollar volume, cross-border volume, and switched transactions. Feedback suggests this growth spans both the core network and international activity.
Profitability: Operating income and net income grew faster than revenue in Q2 2026 (operating income +17%, net income +19%), with full-year 2025 also showing double-digit profit increases. These results indicate operating leverage and earnings expansion alongside sales growth.
Diversified Revenue Streams: Value-added services and solutions grew roughly 18%–23% in recent periods and now comprise a substantial share of total revenue, including cybersecurity, fraud prevention, authentication, and analytics. This broadens the business beyond card transactions and supports continued expansion.
Ericsson builds the digital connectivity the world relies on. Our technology underpins the mobile networks, platforms, and systems that billions of people, businesses, and societies depend on every day. We are a global leader in communications technology, delivering mobile network infrastructure, cloud software, and wireless connectivity solutions for service providers and enterprises worldwide. Our networks support connectivity across 180+ countries, helping...

Ericsson's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests quarterly reported sales and organic growth have recently improved, led by the Networks business with 7% organic growth in Q3 2026 and a 6% increase in reported sales to SEK 59.5B. Underlying momentum is also visible year-to-date with 4% organic sales growth through September 2026 despite currency and portfolio effects.
Cost & Operational Efficiency: Feedback suggests margins and efficiency have seen progress, with adjusted gross margin near prior-year levels and prior-year improvements in adjusted EBITA and gross margin indicating disciplined execution. This operational resilience supports stability even when headline revenue is uneven.
Strong Market Position & Advantage: Feedback suggests Ericsson retains a strong competitive footing in mobile network infrastructure, with Networks as a clear growth engine across regions like Japan, India, Vietnam, and the Middle East. The company is viewed as a leading vendor in 5G RAN and core markets, underpinning demand durability.
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has risen consistently, with annual growth in the high single digits and the latest quarter showing double-digit year-over-year increases, and management raising full-year growth guidance. Organic constant-currency expansion in the latest quarter indicates underlying momentum beyond acquisitions and FX.
Profitability: Profitability is improving alongside sales, as net income and adjusted diluted EPS increased year over year in the latest quarter. Full-year results also showed higher net income and adjusted EBITDA.
Market Expansion: Growth appears across U.S. Markets and internationally, with U.S. Financial Services leading and international results positive on an organic constant-currency basis. The company is extending its reach through moves such as acquiring a majority stake in Trans Union de México.

CrowdStrike has redefined security with the world’s most advanced cloud-native platform that protects and enables the people, processes and technologies that drive modern enterprise. Tested and proven, the world's largest organizations trust CrowdStrike to stop breaches with unparalleled protection against the most sophisticated cyberattacks. The CrowdStrike culture has been built upon our Core Values since the day we began. We...
CrowdStrike's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose 26% year over year to about $1.47B in Q2 FY2027, while ARR increased roughly 25% to $5.84B and the full‑year outlook was raised. These indicators point to durable top‑line momentum across recent quarters and fiscal years.
Healthy Cash Flow: Quarterly free cash flow increased to about $377M (from ~$284M a year earlier) and operating cash flow reached roughly $530M. Rising cash generation alongside growth supports operating flexibility and investment capacity.
Product Line Growth: Adoption across the Falcon platform is deepening, with record net new ARR of about $333M (+51% YoY) and rapid expansion in offerings such as Falcon Flex ARR (exceeding ~$2.29B, up ~101% YoY). Cloud and identity security ARR also expanded meaningfully, indicating broader portfolio traction.
Flywire is a global payments enablement and software company. We combine our proprietary global payments network, next-gen payments platform and vertical-specific software to deliver the most important and complex payments for our clients and their customers.
Flywire's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue up 27.2% year over year in Q2 2026, with full-year 2025 revenue rising 26.6% to $623 million. Management also raised its 2026 growth outlook, reinforcing the trajectory.
Market Expansion: Client additions of 200+ across 45 countries in both Q1 and Q2 2026 and growth beyond education into travel, healthcare, and B2B indicate a broadening footprint. Education revenue outside core markets growing 30%+ further supports geographic expansion.
Profitability: Adjusted EBITDA increased 44.5% in Q2 2026 with margin expansion, and full-year 2025 reported positive net income. These trends suggest improving earnings power alongside scale.

Octus, was founded in 2013 with a simple conviction: credit decisions deserve clarity, not chaos. Markets were fragmented. Intelligence was gated. Data lived in silos. Professionals were forced to stitch together incomplete pictures while the clock kept running. We built Octus to change that. Octus is the essential credit platform that tracks the entire credit lifecycle. From origination and underwriting to...
Octus's Top Stability & Growth Strengths
Strong Revenue Growth: Double-digit compound revenue growth since 2022 is reported, with expectations to continue at a low-to-mid double-digit rate post-acquisition. ARR reportedly more than tripled during roughly four years under Permira, reinforcing momentum in recurring subscription revenue.
Profitability: An approximately 40% adjusted EBITDA margin is cited for 2026, indicating meaningful earnings at scale. This profitability accompanies a 2026 revenue outlook above $300 million.
Product Line Growth: The offering has broadened beyond intelligence into AI capabilities, covenant and deal-term analytics, and portfolio-management and trading workflows via acquisitions like Sky Road and LevPro. Permira also highlights that the number of products sold into credit markets nearly doubled.

Light & Wonder is a leading cross-platform global game company focused on creating new worlds where players can immerse themselves in dynamic casino, online or mobile games. Headquartered in Las Vegas, Nevada, with nearly 5,000 employees, the company has locations on six continents.
Light & Wonder's Top Stability & Growth Strengths
Profitability: Operating earnings have been rising faster than sales, with AEBITDA and margins improving year over year and into 2026. Q2 results also showed a notable uptick in reported net income, reinforcing earnings momentum.
Healthy Cash Flow: Cash generation strengthened materially, with operating and adjusted free cash flow increasing and outpacing revenue growth in both 2025 and the first half of 2026. This trend supports balance‑sheet goals and ongoing investment capacity.
Diversified Revenue Streams: Growth is being led by recurring gaming operations and iGaming, while charitable gaming adds another contributor, indicating less reliance on one-time hardware sales. The expanding premium installed base underpins a larger stream of recurring revenue.

LogicMonitor® is the AI-first hybrid observability platform powering the next generation of digital infrastructure. LogicMonitor delivers complete visibility and actionable intelligence across on-premises, cloud, and edge environments. By anticipating issues before they strike, optimizing resources in real time, and enabling faster, smarter decisions, LogicMonitor helps IT and business leaders protect margins, accelerate innovation, and deliver exceptional digital experiences without compromise....

LogicMonitor's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have progressed from more than $300 million in June 2025 to more than $400 million by May 2026, signaling clear top-line momentum. Growth among higher‑spend enterprise accounts is also highlighted as a key contributor.
Investor Backing & Capital Strength: An $800 million equity and strategic financing round at an approximately $2.4 billion valuation is described as providing substantial capacity to fund expansion. Ongoing sponsorship by the controlling shareholder is also noted.
Product Line Growth: AI-led offerings such as Edwin AI are described as contributing a significant share of bookings with very rapid recurring‑revenue growth. The Catchpoint acquisition further extended capabilities into internet performance and digital experience monitoring.
Optum, part of the UnitedHealth Group family of businesses, is a global organization that delivers care, aided by technology to help millions of people live healthier lives. The work you do with our team will directly improve health outcomes by connecting people with the care, pharmacy benefits, data and resources they need to feel their best. Here, you will find...

Optum's Top Stability & Growth Strengths
Profitability: Operating earnings and margins improved notably in 2026, with Q3 operating earnings up sharply year over year and the operating margin rising to 5.6%. Feedback suggests earnings resilience is being supported by operational changes and a shifting business mix.
Strong Revenue Growth: Reported annual revenue expanded from $226.6B in 2023 to $270.6B in 2025, including roughly 12% growth in 2024 and 7% in 2025. This establishes a robust multi‑year revenue trajectory even as recent growth rates have moderated.
Cost & Operational Efficiency: Cost controls and operational improvements are described as lifting earnings despite lower revenue in 2026. Optum Health’s operating earnings rose from $41M to $735M year over year while serving fewer value‑based patients, indicating stronger execution.
ZS is a management consulting and technology firm that partners with companies to improve life and how we live it. We transform ideas into impact by bringing together data, science, technology and human ingenuity to deliver better outcomes for all. Founded in 1983, ZS has more than 15,000+ employees in over 40 offices worldwide.
ZS's Top Stability & Growth Strengths
Strong Hiring & Retention: Headcount and hiring momentum are evident, with third-party estimates showing growth from roughly the mid‑teens of thousands in 2024 to 20,000+ by 2025–2026 and plans to hire thousands, alongside new capacity such as the Hyderabad operations center. This suggests the company is scaling delivery and talent depth across geographies.
Innovation-Driven Growth: The firm has expanded into AI and digital offerings, including its ZAIDYN platform, acquisitions like Digital Additive and Torrent Consulting, and launches such as Myelo developed with the International Myeloma Foundation. These moves indicate investment beyond traditional consulting into scalable, tech‑enabled services.
Market Expansion: A dedicated mid‑cap pharmaceutical vertical and the opening of an operations center in Hyderabad point to deliberate expansion in target segments and delivery footprint. These steps signal efforts to broaden served markets and strengthen execution capacity.
Zscaler accelerates digital transformation so our customers can be more agile, efficient, resilient, and secure. Our cloud native Zero Trust Exchange platform protects thousands of customers from cyberattacks and data loss by securely connecting users, devices, and applications in any location.

Zscaler's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue and annual recurring revenue each rose 25% in fiscal 2026, with fourth-quarter revenue also up 25% year over year. Management still expects continued double-digit growth in fiscal 2027, albeit at a slower pace.
Healthy Cash Flow: Operating cash flow reached about $1.13 billion and free cash flow was roughly $779.1 million in fiscal 2026. This points to robust cash generation alongside expansion.
Product Line Growth: The platform is expanding into AI security, data security, SASE, and agentic security operations. Security-for-AI bookings were reported to increase more than 50% sequentially in the fourth quarter, indicating early traction.
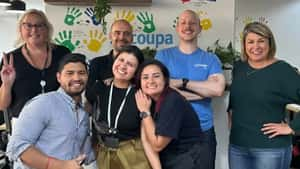
Coupa is a global technology company that helps businesses run smarter by connecting all the ways they spend money — from procurement and expenses to payments and supply chain decisions — in one intelligent platform. In simple terms, Coupa gives organizations the visibility and control they need to make better financial choices, reduce waste, and drive real impact. It’s where...
Coupa's Top Stability & Growth Strengths
Strong Revenue Growth: Record quarterly revenue in fiscal Q4 FY2026 and earlier double-digit bookings growth indicate continued top-line momentum. ARR is described as continuing to grow, even though detailed year-over-year revenue rates are not fully disclosed.
Customer Loyalty & Retention: Nearly 1,300 organizations renewed or expanded in FY2026, with subsequent quarters showing hundreds more renewals alongside new customer wins. High gross retention is highlighted, reinforcing durable, recurring relationships.
Innovation-Driven Growth: Expansion of AI-powered agents to hundreds of customers, acquisitions such as Rossum and Tonkean, and a five-year collaboration with AWS point to product-led growth. Rising platform usage into hundreds of billions of dollars per quarter further supports adoption and ecosystem scale.
At Rapid7, our vision is to create a secure digital world for our customers, our industry, and our communities. We do this by harnessing our collective expertise and passion to challenge what’s possible and drive extraordinary impact. We’re building a dynamic and collaborative workplace where new ideas are welcome. Protecting 11,000+ customers against bad actors and threats means we’re continuing...
Rapid7's Top Stability & Growth Strengths
Profitability: Operating and net income remained positive even as revenue softened in recent quarters. This indicates an earnings base that is holding up during a period of slower demand.
Healthy Cash Flow: Free cash flow stayed positive with meaningful generation quarter to quarter, and guidance points to continued cash production. Liquidity is reinforced by a sizable balance of cash, cash equivalents, and government securities.
Future-Ready Strategy: Management is concentrating investment on the Command Platform, detection and response, exposure management, and AI-enabled security operations. This refocus aims to position the portfolio for a return to growth once the transition progresses.
.jpg)
Acquia is the open digital experience company. We provide the world's most ambitious brands with products built around Drupal to allow them to embrace innovation and create customer moments that matter. At Acquia, we believe in the power of community and collaboration — giving our customers and partners the freedom to build tomorrow on their terms.

Acquia's Top Stability & Growth Strengths
Strong Market Position & Advantage: Acquia is portrayed as a recognized enterprise DXP/CMS vendor with thousands of customers, broad global operations, and repeated inclusion in major analyst evaluations. This positioning indicates durable competitive footing across digital experience and Drupal-centered content management.
Innovation-Driven Growth: Ongoing launches and enhancements such as Acquia Source and AI-enabled capabilities, along with acquisitions like Widen and Monsido and alliances including Vercel, indicate sustained platform expansion. These moves suggest a strategy to deepen wallet share within existing accounts and open adjacent opportunities.
Investor Backing & Capital Strength: A majority investment by Vista Equity Partners since 2019 is described as enabling accelerated product development and global expansion. This backing points to access to capital and a continued growth mandate.

IDeaS is a company of innovators, collaborators, and educators. Founded in 1989, with the goal to revolutionize revenue management for businesses worldwide. The company's founders were pioneers in revenue science, and IDeaS has continued to lead the way in this field ever since, particularly in the hospitality and travel industries. We use advanced mathematics and industry expertise to turn data into...

IDeaS's Top Stability & Growth Strengths
Market Expansion: Geographic reach is broadening with notable revenue increases in markets like Greece and Germany, expanded deployments in Saudi Arabia, and new agreements with multi‑property hotel groups in the U.S. Partnerships and integrations in regions such as DACH and with platforms like Medialog further open access to additional properties and countries.
Product Line Growth: Adoption of newer offerings is accelerating, with more than 1,600 hotels implementing a newly launched market‑intelligence product within 100 days and strong uptake of Optix among targeted client segments. The portfolio is expanding beyond core RMS into commercial strategy, business intelligence, and adjacent hospitality segments.
Customer Loyalty & Retention: A very high client‑retention rate and a footprint exceeding 34,000 properties across more than 170 countries indicate durable relationships and substantial scale. This stability provides a solid base for cross‑selling newer solutions and continued international expansion.
At Finastra our purpose is to unlock the power of finance for everyone & redefine finance for good. We’re the orchestrator of open finance; building and delivering innovative, next-generation technology on our open Fusion software architecture and cloud ecosystem. We’re one of the world’s largest FinTechs, working with over 9,000 customers including 90 of the top 100 banks globally. We’re...
Finastra's Top Stability & Growth Strengths
Strong Market Position & Advantage: Finastra is frequently positioned at or near the top in several core banking-technology segments, with multiple analyst “Leader” placements and strong standings in wholesale payments and corporate lending platforms. The scale of its installed base and penetration among large global banks further supports durability in mission-critical workloads.
Strong Revenue Growth: Finastra has stated it delivered record financial performance and double-digit ARR growth entering 2025, indicating momentum in its recurring revenue engine. Continued sales traction signals commercial expansion even as the company reshapes its portfolio.
Future-Ready Strategy: Finastra has emphasized reinvestment into core areas like Lending, Payments, and Universal Banking following the Treasury & Capital Markets divestiture, suggesting a sharper strategic focus. Geographic investments (new/expanded hubs and innovation centers) and emphasis on cloud and AI-enabled software align with longer-term modernization demand.



